Maximizing corporate retained earnings through lawful tax planning, capital asset depreciation modeling, and statutory deduction frameworks.
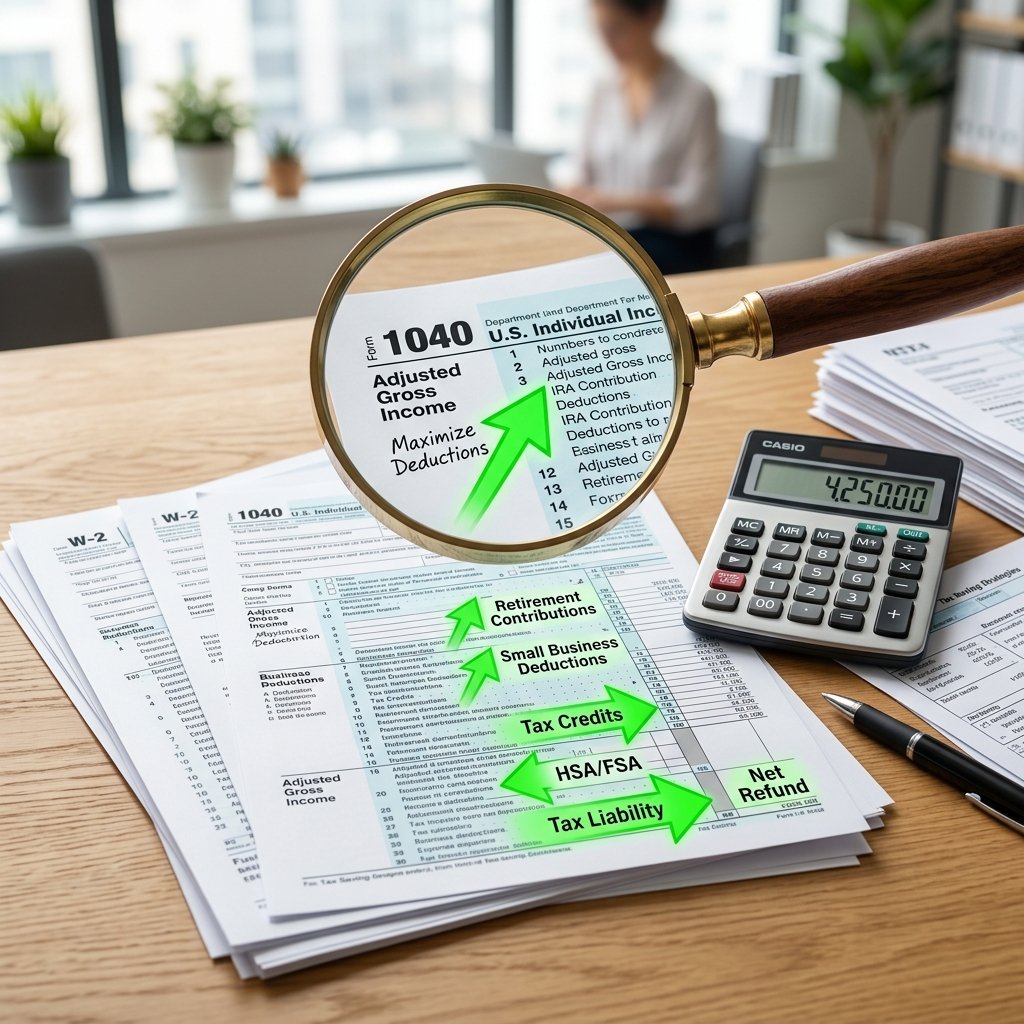
Every rupee preserved through proactive, compliant tax planning is a direct addition to your corporate retained earnings. For Indian small and medium enterprises, navigating the provisions of the Income Tax Act, 1961 ensures balance sheets remain robust for future debt underwriting.
Eligible resident enterprises with gross receipts up to ₹2–3 Crore (subject to 95% digital receipts threshold) can declare a presumptive net income of 6% (digital receipts) or 8% (cash receipts), significantly minimizing administrative and audit overheads.
Pre-incorporation advisory costs, project report preparation fees, legal drafting charges, and statutory ROC registration fees can be amortized and deducted in 5 equal successive annual installments from corporate taxable profits.
Acquiring new manufacturing plant and machinery allows industrial units to claim standard block depreciation plus an additional 20% initial depreciation allowance in the year of commissioning, substantially lowering taxable income.
Recognized startups incorporating after April 1, 2016 can secure approval from the Inter-Ministerial Board to claim a 100% deduction of profits for 3 consecutive financial years out of their first 10 operational years.
FundingBridge Business Solution Private Limited reviews enterprise balance sheets, compliance dossiers, and capital structures to ensure seamless eligibility for statutory schemes and debt facilities.
Tell us what you need and our funding specialists will help you explore suitable funding options securely.
Share a few details and our team will get in touch.
Thank you for contacting FundingBridge Business Solution Private Limited.
Our funding specialists will review your requirement and get in touch with you shortly.